IAS 29 – Financial Reporting in Hyperinflationary Economies
3
Hours
Intermediate
Level
Flexible
Schedule
Hours
Level
Schedule
Learning outcomes
The objectives and scope of IAS 29 and when the standard applies.
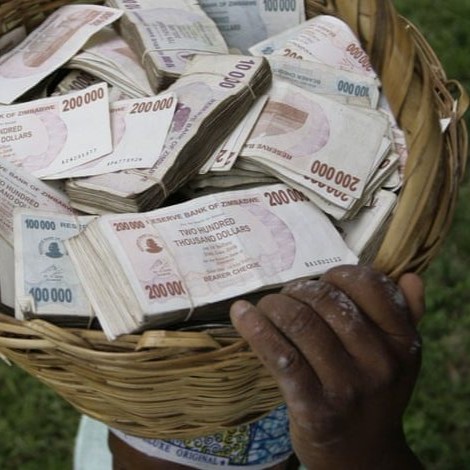
How to identify a hyperinflationary economy and key indicators of hyperinflation.
The restatement process for financial statements under IAS 29, including monetary and non-monetary items.
Methods for adjusting equity, income, and cash flow statements for the effects of hyperinflation.
Practical examples of applying IAS 29 and interpreting restated financial information.
Course contentParticipants
Accountants and finance professionals working in or with hyperinflationary economies.
Auditors who review financial statements prepared under IAS 29.
Financial controllers and CFOs responsible for reporting in volatile economic environments.
Advisors and consultants supporting clients with IFRS compliance in challenging market conditions.
Pre-requisites
A background in accounting, finance, or business administration.
Basic understanding of IFRS financial statements and reporting principles.
Experience with inflation-adjusted reporting is beneficial but not mandatory.
Add this credential to your LinkedIn profile, resume, or CV.
Course Content
Purpose and effective date of IAS 29.
Indicators of hyperinflation under IFRS.
Restatement of non-monetary items and monetary items.
Impact of hyperinflation on equity, profit, and loss.
Adjusting comparative amounts and disclosures.
Practical application examples and case studies.
Form
For any questions you may have or to respond to examples discussed in the course, please feel free to fill in the form provided. Your inquiries and insights are valuable, and we’re here to help clarify and deepen your understanding.
Or contact us through our mail